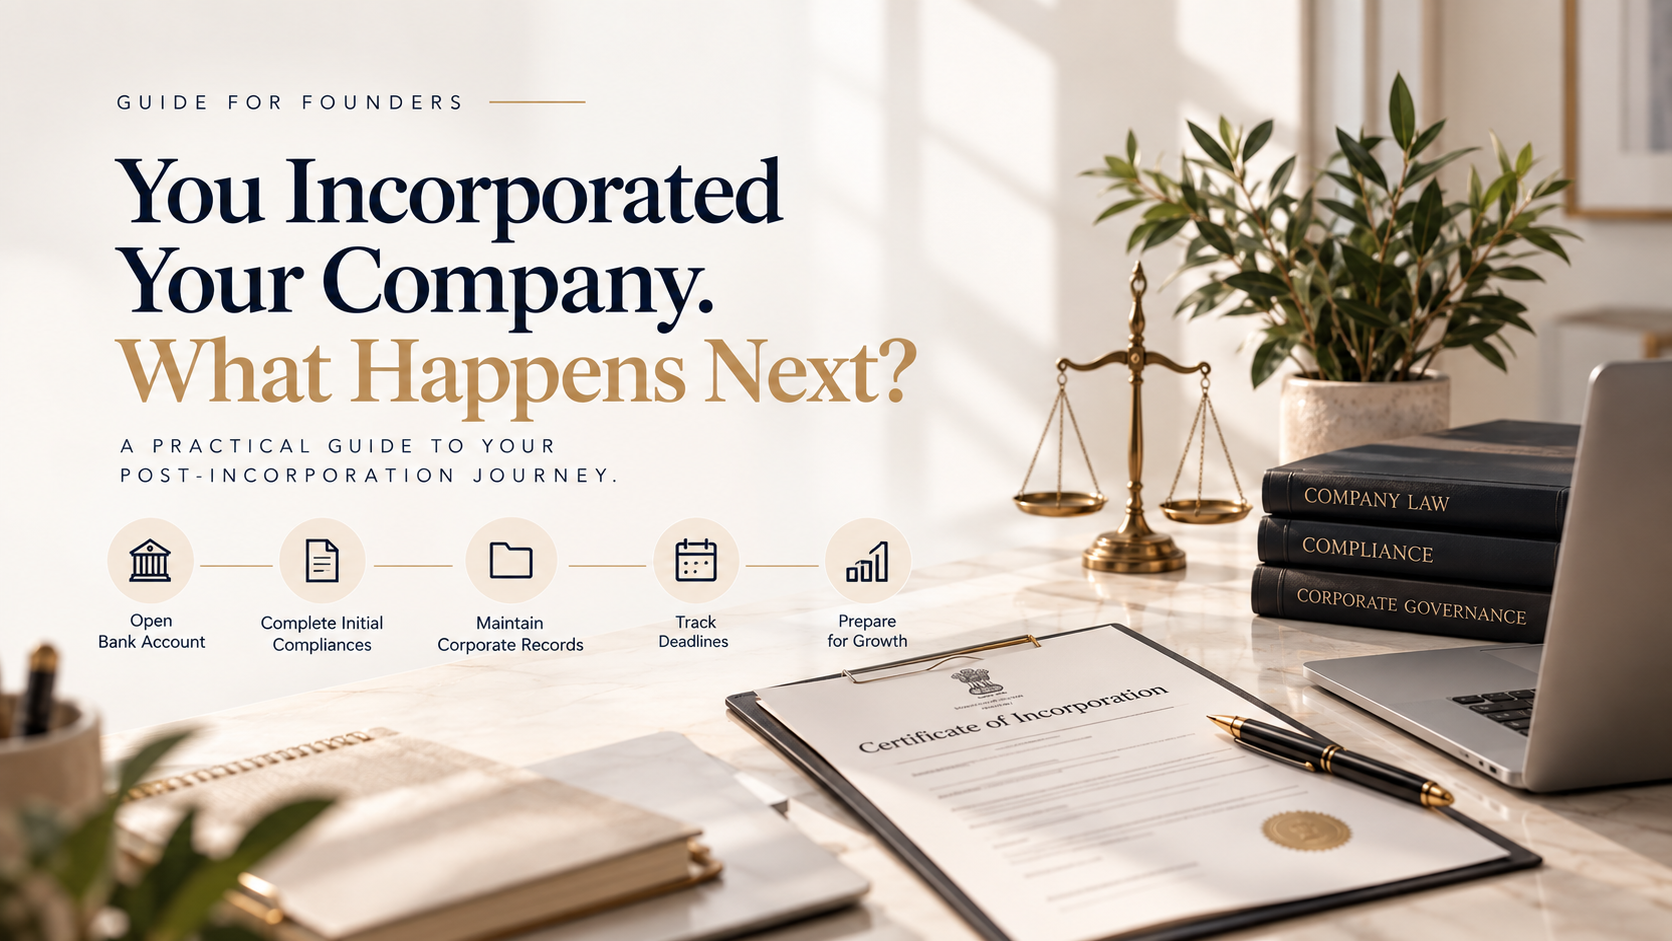
Incorporating a company is an important milestone, but registration is only the beginning of your compliance journey.
Once your company is incorporated, there are several important legal, financial and administrative responsibilities that founders and directors need to take care of. Missing these early requirements can create unnecessary compliance issues later.
Here is a practical post-incorporation checklist for a newly incorporated company in India.
1. Open the Company’s Bank Account
After incorporation, the company should have a dedicated bank account for its business transactions.
Avoid mixing personal and business transactions. Maintaining separate financial records from the beginning makes accounting, reporting and future due diligence much easier.
2. Complete Initial Statutory Requirements
Depending on the company's structure and circumstances, certain post-incorporation compliances may need to be completed within prescribed timelines.
This can include matters relating to:
Appointment of the first auditor
Issue and allotment of shares
Subscription money
Registered office
Statutory registers and records
Director-related requirements
The exact requirements and timelines depend on the company's circumstances and applicable law.
3. Maintain Proper Corporate Records
A company should maintain its important corporate documents from day one.
These may include:
Certificate of Incorporation
MOA and AOA
Share certificates
Board resolutions
General meeting records
Statutory registers
Director and shareholder information
Important contracts and agreements
Good documentation is not just about compliance. It also helps when the company raises funds, brings in investors, enters into major contracts or undergoes due diligence.
4. Understand Your Annual Compliance
Incorporation does not mean compliance ends after receiving the Certificate of Incorporation.
Companies generally have continuing obligations such as maintaining books and records, conducting required meetings, preparing financial statements and filing applicable forms and returns with the MCA.
The exact requirements vary depending on the type and size of the company and other applicable regulations.
5. Track Important Deadlines
One of the simplest ways to avoid compliance problems is to maintain a compliance calendar.
Track:
ROC/MCA filing deadlines
Director-related compliances
Annual filing requirements
Tax and GST-related deadlines, where applicable
Board and shareholder meetings
Licence and registration renewals
Other industry-specific regulatory requirements
A missed deadline can become more complicated and expensive to resolve later.
6. Review Your Business Structure as You Grow
Your compliance requirements may change as your business grows.
For example, raising investment, issuing new shares, appointing or changing directors, entering into foreign transactions, changing the registered office or restructuring the business can create additional corporate and regulatory requirements.
This is why compliance should be treated as an ongoing business function rather than a one-time activity.
Compliance Is More Than Filing Forms
A common misconception is that corporate compliance simply means submitting forms to the MCA.
In reality, good compliance involves maintaining proper records, following the correct approval process, understanding regulatory requirements and ensuring that important business decisions are properly documented.
For founders, the objective should not simply be to "file on time."
It should be to build a business that is properly structured, well-documented and prepared for growth.
Final Checklist
Before moving forward, ask:
☐ Is the company's bank account operational?
☐ Are the initial statutory requirements completed?
☐ Are corporate records properly maintained?
☐ Are important compliance deadlines being tracked?
☐ Are financial and accounting records organised?
☐ Are board and shareholder decisions properly documented?
☐ Is the company prepared for future fundraising, expansion or due diligence?
If you are unsure about your company's post-incorporation requirements, getting the right professional guidance early can help prevent avoidable compliance issues later.

Comments
No comments yet. Be the first to share a note on this article.
Leave a comment